In this article
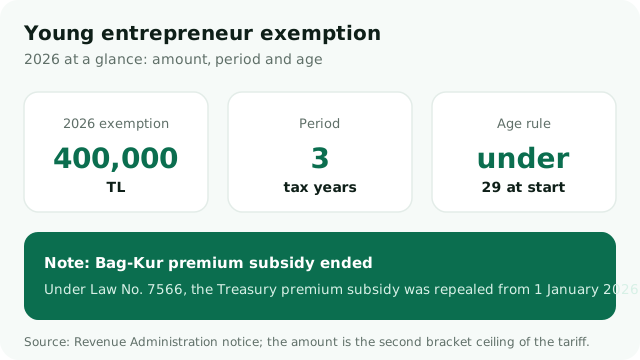
Short answer: The young entrepreneur exemption sets aside part of the business, agricultural or professional earnings of a full taxpayer who is registered for income tax for the first time and who has not turned 29 on the start date. For 2026 the amount is TL 400,000. It runs for three tax years including the calendar year activity begins. Unused amount does not carry forward. From 1 January 2026 the Bağ-Kur premium subsidy for young entrepreneurs has been repealed; the income-tax exemption remains.
Searches often mix “young entrepreneur exemption” with “young entrepreneur social-security support”. One is income tax. The other was a one-year Bağ-Kur premium subsidy. This guide separates them. Opening a sole proprietorship is in how to open a sole proprietorship. The choice of type is in sole trader or limited company.
Who qualifies, and who does not?
The relief rests on provisional article 20 of the Income Tax Law. It applies to a full taxpayer natural person whose income-tax registration is opened for the first time and who has not turned 29 on that start date. A limited or joint-stock company is a legal person; the exemption does not reduce its corporate tax. A shareholder who also runs a separate trade or profession in their own name is assessed on that activity separately.
Commencement must be notified within the statutory period under the Tax Procedure Law. A late notice can kill the relief even when age and first registration are otherwise met. The person must work in the business in person or direct and manage it. Employing an apprentice, journeyman or helper does not break that rule. Temporary absence for illness, military service or similar necessity does not break it either.
If the activity sits in a simple partnership or a partnership of natural persons, every partner must meet the conditions on the start date. One partner aged 30 keeps the others out. Taking over a business or professional practice from a spouse or a blood or in-law relative up to the third degree (except transfer to spouse and children on death) ends the relief. Joining an existing business later as a partner has the same effect.
Starting a second activity while the first continues does not extend the period. The three years are tied to the first activity. Ceasing and later starting again breaks the “first registration” test; a new opening after cessation does not revive the exemption. Taxpayers moving from the simplified method to the real method after Communiqué No. 327 may enter the relief if they meet the conditions. That file is not a one-line change.
What is the 2026 amount?
| Year | Exemption amount | Basis |
|---|---|---|
| 2025 | TL 330,000 | Second bracket ceiling of the tariff |
| 2026 | TL 400,000 | Second bracket ceiling of the tariff |
| Later years | Updated with the tariff | Not a fixed TL 75,000 |
Older texts still show TL 75,000. Since Law No. 7440 the amount follows the second bracket of the income-tax tariff. The Revenue Administration’s 2026 notice states TL 400,000. Memorising a single figure every year is wrong. When the bracket moves, the exemption moves.
Example: if 2026 business profit from this activity alone is TL 400,000 and there is no other taxable income to declare, the whole amount sits inside the exemption. If profit is TL 550,000, TL 400,000 is set aside and the remaining TL 150,000 is taxed under the tariff. To make the arithmetic concrete, use the income-tax calculator; strip the exemption from the base first.
If there is other income to declare—rent, wages, investment income—the exemption applies only to business, agricultural and professional earnings. It applies once to the total of those earnings; it does not create a separate TL 400,000 for each line of work. Even when earnings are below the ceiling, or there are none, an annual income-tax return is still filed. Unused relief does not roll into the next year.
The Bağ-Kur premium subsidy has ended
From 1 June 2018, for a year, the Treasury could cover premiums of young entrepreneurs who first became insured under article 4/1-b. Article 23 of Law No. 7566, published in the Official Gazette of 19 December 2025 No. 33112, repealed that subsidy with effect from 1 January 2026. The Revenue Administration notice draws the same line: the premium subsidy is gone; the earnings exemption remains.
A 28-year-old who opens a sole proprietorship in 2026 may still use the income-tax exemption if the conditions are met, and pays Bağ-Kur under the ordinary rules. Premium amounts are in Bağ-Kur premiums 2026. “I am a young entrepreneur, so I pay no premium for a year” is no longer true for 2026 openings.
The exemption does not affect tax withheld under article 94 of the Income Tax Law. Marketplace or rent withholding is not clawed back merely because the exemption exists; set-off is discussed on the annual return. Do not put withholding and the exemption on the same scale.
Couriers, e-commerce and freelancers
A motorcycle courier working with platforms usually opens a sole proprietorship. If age and first registration are met, the exemption can cover that profit. The opening sequence is in courier sole proprietorship; the tax lines are in the courier tax guide. The exemption does not erase a Bağ-Kur debt; the premium is still paid.
A marketplace seller enters through the same door. Registered as a sole trader and meeting the conditions, up to TL 400,000 of 2026 profit may be exempt. If a limited company was formed, the exemption does not touch corporate tax; the choice of type must be settled first. Formation is in forming a company for e-commerce; monthly books are in e-commerce accounting.
A self-employed professional may also use the professional-earnings exemption. Withholding on the receipt does not replace it. The receipt breakdown is in the freelance receipt calculator. If the line of work changes but the remaining period and the conditions hold, the exemption can continue; the clock does not reset.
How is the file set up in Ankara?
The exemption does not appear by itself on the return. The file must show that commencement was notified on time, that age held on the registration day, and that the activity is a first registration. In Ankara the tax-office record often moves through digital channels; the inspection still comes to the address. Address and sign are covered in a tax office inspection.
Our office is in Çankaya, a short walk from Kızılay. Three items are enough for the first meeting: identity, a print or screen of the commencement notice, and a short note on the type of activity. A courier adds the platform contract; an e-commerce seller adds the shop panel. Filing days are in the 2026 tax calendar.
Write down which of the three years you are in at the start of each year. For a business opened in 2026 the years are 2026, 2027 and 2028. 2029 earnings sit outside this exemption. It is not stretched with “three years are up, keep the fourth the same”. When the period ends, the full tariff applies; preparation starts before the last year’s return.
Frequently Asked Questions
How much is the 2026 young entrepreneur exemption?
TL 400,000. That figure is the second bracket ceiling of the income-tax tariff. In 2025 it was TL 330,000. It is not a fixed TL 75,000.
Does the Treasury still cover Bağ-Kur premiums?
No. Law No. 7566 repealed the young entrepreneur insurance-premium subsidy from 1 January 2026. The income-tax exemption remains in force separately.
If I open after turning 29, can I still use it?
No. The measure is the start date of the registration. If you have already turned 29 on that day, the exemption does not arise. A later birthday does not rewind the test.
Does a limited company get the exemption?
The exemption does not reduce a limited company’s corporate tax. It is for a natural person’s business, agricultural or professional earnings. A sole proprietorship or a freelance practice sits in that scope.
If earnings are below TL 400,000, do I skip the return?
The return is still filed. Unused exemption does not carry forward. Even with no earnings, the annual return duty remains.
In short
The 2026 young entrepreneur exemption is TL 400,000. Full taxpayers under 29 at first income-tax registration may use it for three tax years. Notice timing, personal work or management, and not taking over a relative’s business must show in the file. The Bağ-Kur premium subsidy is gone from 2026; premiums follow the ordinary rules. A limited company’s corporate tax is outside this exemption.
To set up your opening and first return in Ankara together, see tax advisory and bookkeeping, and send us the file.