In this article
Short answer: If you are starting alone, with modest turnover and a simple activity, a sole proprietorship is usually faster and cheaper. If you will take a partner, want liability limited to the capital you commit, or aim at corporate customers and tenders, a limited company fits better. The right choice depends on expected profit, risk and whether anyone else will own a share.
In Ankara this is almost always the first question. Both structures are legal and both need an accountant. The difference is the name of the tax, who owes the debts, and how easy it is to add a partner later. This is a framework; the numbers change with your own profit estimate.
The two structures side by side
| Topic | Sole proprietorship | Limited company |
|---|---|---|
| Identity | You and the business are the same person | A separate legal entity |
| Tax | Income tax, rising rates | Corporate tax, a single rate |
| Social security | Bağ-Kur (4/b) | Partners on Bağ-Kur; employees on 4/a |
| Liability | Personal assets for trade debts | As a rule, limited to committed capital |
| Setup | Tax office registration | MERSİS, articles, trade registry, tax office |
| Taking profit out | You may draw cash; tax follows profit | Salary or dividend; dividends are withheld |
“Liability is limited to capital” does not always cover tax and social security debts. For public receivables, and in some signing situations, partners can still be pursued. A limited company is not an automatic shield against every debt. That point belongs in the conversation before you form the company.
The tax burden follows profit
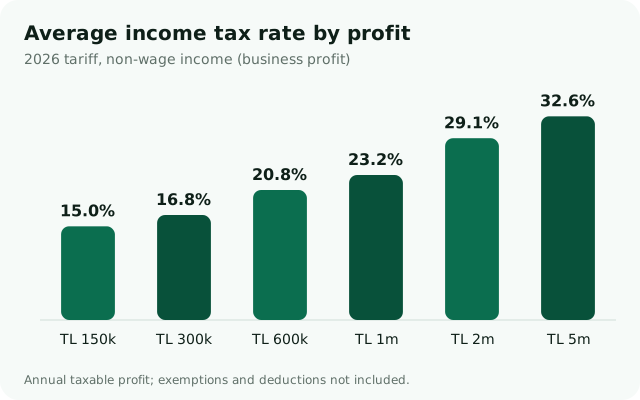
In a sole proprietorship, profit falls into the income tax tariff. For 2026 non-wage income the bands step up: 15% up to a set amount, then 20%, 27%, 35% and 40% at the top. The chart shows the average rate before exemptions and deductions. As profit grows, the share you pay rises.
In a limited company, corporate profit is charged corporate tax and the rate does not step up by band. If you distribute profit to the partners, dividend withholding applies as well. If you leave the profit in the company, that withholding does not arise that year. So “a limited company always pays less tax” is wrong. At low profit, the sole trader’s first 15% band can sit below the corporate rate. At high, steady profit, the limited company is easier to predict.
Try your own estimate with the income tax calculator. Compare the same profit figure in both structures. Using turnover instead of profit breaks the comparison.
Setup and the monthly load
A sole proprietorship opens with a business address and a tax office registration. No capital is blocked and no articles are filed at the trade registry. The steps are in how to open a sole proprietorship. A limited company needs a name search, articles, a MERSİS application, the registry and a tax registration. The Ankara sequence is in company formation, step by step.
The monthly load differs too. Both pay Bağ-Kur; the amounts are in Bağ-Kur premium 2026. A limited company can add notary, registry and, in some years, an independent-audit threshold. Payroll is similar in both once you have employees.
Six decision criteria
- Is there a partner? If a second person will own a share, a limited company puts the split in the articles. You cannot add a partner to a sole proprietorship; an ordinary partnership is a different structure.
- How much personal risk? Large purchases, imports or long commitments point to a legal entity. A small service business can stay a sole proprietorship.
- Who is the customer? Some corporate buyers and tenders want the invoice issuer to be a company. Ask before you form anything.
- What will you do with the profit? If you live on drawing all of it, the cash in a sole proprietorship is already yours. A limited company needs a payroll salary or a dividend.
- Name and title. A limited company’s trade name is protected at the registry. A sole proprietorship is opened in your own name; a shop sign is separate from a trademark.
- Closing. A sole proprietorship can close with a cessation notice to the tax office. Liquidating a limited company takes longer. That matters for a short trial. See company changes and liquidation.
Can you switch later?
Moving from a sole proprietorship to a limited company means forming a new company and transferring the activity and some assets. Customer contracts, e-Invoice series, bank accounts and employee notifications are set up again. It is possible, but staying two years in the wrong structure creates extra tax and contract work. If you are unsure, a meeting before formation is cheaper than a conversion afterwards.
The other direction happens too: a limited company that has shrunk can be liquidated and replaced by a sole proprietorship. Staff, stock and live contracts make the order matter.
The practical difference in Ankara
Both structures can be run from our Çankaya office or online. A sole proprietorship’s tax registration is often completed through the digital tax office. A limited company may still need a registry appointment and a signature in Ankara. The rest of the remote process is in how online accounting works.
One-person work such as courier delivery, marketplace selling or freelance work often starts as a sole proprietorship. A limited company is reconsidered when the team, the stock or a partnership grows. The courier-specific sequence is in opening a courier sole proprietorship.
A worked example
Take a sole proprietorship with TL 300,000 of taxable profit. On the 2026 non-wage tariff the first TL 190,000 is taxed at 15% and the remaining TL 110,000 at 20%. Tax is about TL 50,500, an average of 16.8%. At TL 150,000 the whole profit stays in the first band and tax is TL 22,500, or 15%. At TL 600,000 the higher bands apply and the average rate rises, as the chart shows.
The example leaves out exemptions, donations, prior-year losses and the Bağ-Kur deduction. The premium can be written as an expense, so it reduces taxable profit. A comparison that ignores it points the wrong way. On the limited company side, corporate tax is a single rate, and withholding is added only if profit is distributed. “A sole trader always pays more” starts to be true only once profit reaches the upper bands.
Build the example with your own turnover only after expenses. If turnover is TL 1,000,000 and documented expenses are TL 850,000, taxable profit is TL 150,000. Treating turnover as profit can push you into a limited company you do not need.
Frequently Asked Questions
Does a limited company need a large capital?
The minimum capital is set by the legislation and can change. The current figure is confirmed on the day you form the company. You do not always pay the whole amount into the till on day one; the articles set the commitment and the payment period.
Can I use my home address for a sole proprietorship?
If the activity code and municipal rules allow it, some businesses can use a home address. Receiving customers, storing goods or manufacturing may also need a workplace licence. Settle the activity code before you choose the address.
Which one has cheaper Bağ-Kur?
The premium follows earnings, not the legal form. The minimum starts from the same floor in both. The discount depends on paying on time and having no debt.
Is there a penalty for choosing the wrong one?
Choosing the wrong type is not itself a tax penalty. The real cost is unnecessary tax, personal liability, or a later transfer done in the wrong structure.
Final word
A sole proprietorship fits a simple start and lower profit. A limited company fits a partnership, limited liability and corporate work. Compare tax on profit after expenses, not on turnover.
For a comparison before you form anything, see company formation, or contact us to go through your own figures.