In this article
Short answer: A natural person who sells capital shares in a limited company declares a capital gain when there is one. The familiar “hold two years, no tax” rule for joint-stock share certificates does not apply to Ltd shares; holding time alone does not create an exemption. In 2026, TL 150,000 of such gains in a calendar year is exempt; the excess is filed in March of the following year. Papers for the share transfer are stamp-duty exempt; separate protocols that raise the price or add an assignment often fall outside that exemption.
Searches often arrive as “Ltd share sale tax” or “two years passed, I owe nothing”. The second line leaked from the joint-stock certificate file. This guide keeps Ltd shares separate: TCC procedure, Income Tax Law arithmetic, stamp duty and how we build the file in Ankara. If the entity type is still open, see sole trader or limited company; formation order is in company formation in Ankara.
Law first, tax second
Under TCC art. 595, the transfer of capital shares and the act that creates the duty to transfer must be in writing; signatures are notarised. Unless the articles say otherwise, general-meeting approval is required. Without approval the deed may bind the parties yet often fails to change shareholding on the company’s books. Managers register a valid transfer with the trade registry; the share ledger is updated.
The tax file is not built until that chain is complete. “We signed; we will look at the return tomorrow” is not enough. The general-meeting minutes, the notarised deed and the registry extract must sit in one folder. Where a minimum-capital increase is still pending, the share ratio must match the registered capital; that side is in minimum capital increase.
Writing a “symbolic TL 1” price can open an arm’s-length question at the tax office. A sale clearly below market may be recharacterised on review. Putting the same figure on the deed and the bank movement keeps the file defensible.
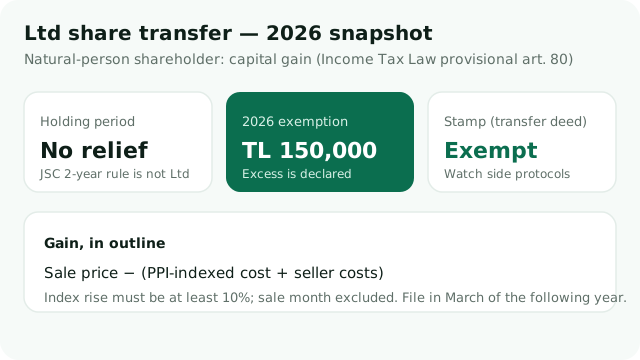
Natural-person shareholder: capital gain
| Point | Ltd share | JSC share certificate (brief) |
|---|---|---|
| Income type | Capital gain (Income Tax Law provisional 80/1-4) | Separate limbs; certificate-linked holding rules exist |
| Two-year hold | Does not create an exemption | May apply to qualifying certificates |
| 2026 exemption | TL 150,000 (annual, relevant gains) | Securities disposals may sit outside this exemption |
| Filing | March of the year after the sale | Per the relevant limb |
In outline the gain is sale price minus (acquisition cost indexed with domestic PPI + costs that stay with the seller). The sale month is left out of the index; a rise of at least 10% is required. Below 10%, indexation is not applied and cost stays as is. Notary fees and similar seller costs may be deducted.
Example: a share bought for TL 200,000 in 2022 and sold for TL 900,000 in 2026. If the index test is met, cost is stepped up; TL 150,000 is exempt from the remainder; the excess enters the non-wage tariff. You can use the income-tax calculator once the exemption line is separated.
If the gain stays under TL 150,000, an annual return often does not arise; article 86 closes filing for amounts inside the exemption threshold. When the threshold is crossed, only the excess is taxed; the exemption does not wipe the whole gain to zero. Several capital gains in the same year share one annual exemption.
Stamp, fees, side protocols
Table (2) to the Stamp Duty Law exempts papers on share transfers of joint-stock, limited partnership by shares and limited companies. Fees Law art. 123 also exempts Ltd share-transfer acts from most fees (court fees aside). Notary fees are not part of that exemption; they follow the tariff.
The trap is the side protocol. A separate text that later raises the transfer price or adds an assignment is, in Revenue Administration rulings, often outside the share-transfer stamp exemption; ad valorem stamp can arise. Do not assume “one envelope, one exemption”. Keep the main deed clean; if price talks move to a protocol, price the stamp first.
When the seller is a company: corporate tax
If the holder is itself a limited or joint-stock company, the file moves to corporate tax. The gain on an affiliate share enters corporate profits. For shares held as fixed assets for at least two full years, Corporate Tax Law art. 5/1-e may apply; the rate is read in its updated form under the Presidential Decision (recently moved from 75% toward 50%). Conditions, reserve accounting and VAT need a separate check; this guide’s main focus is the natural-person shareholder.
Do not mix a share sale with liquidation when the company is closing. Liquidation distributes remaining assets to shareholders; selling the share to a third party is a different act. Closing order is in how to close a company.
The file and the office in Ankara
In our Çankaya office we read the share ratio, the cost evidence and the notarised deed on the same desk. Address: Kültür Mah., İçel Sk. No:3/12, 06420 Çankaya/Ankara — open our office on Google Maps.
Three papers are enough for the first meeting: the notarised transfer (or draft), proof of how the share was acquired (formation, earlier transfer, capital increase), and the general-meeting text if any. The bank credit for the price helps. Filing days are in the 2026 tax calendar; a 2026 sale is filed in March 2027.
If a signature or a face-to-face check is needed at the office a short walk from Kızılay, you come by appointment. Most monthly work runs remotely; a one-off share-transfer file can move by folder or message too. The remote routine is in online financial advisory.
Ankara Trade Registry registration and the tax-office record may not update on the same day. After the shareholding change, managers and signature circulars are revisited so the bank and e-signature file do not stay tied to the old partner. District working patterns are in accounting across Ankara’s districts.
Frequently Asked Questions
I held the Ltd share for two years — no tax?
No. That rule is for qualifying joint-stock share certificates. Holding time alone does not exempt an Ltd capital share.
What is the 2026 exemption?
TL 150,000 on the relevant capital gains. Below it, a return often does not arise; above it, only the excess is taxed.
Is stamp duty due?
The share-transfer paper is exempt. Separate protocols that raise the price or add an assignment may fall outside. Notary fees are paid separately.
What if we write a low price?
Arm’s-length and valuation risk opens. Deed, bank and actual price should share one figure.
Who files the gain?
The natural-person seller files in their own name in March of the following year. The company removes the shareholding from its books; it does not file the seller’s personal gain for them.
In short
An Ltd share sale is not solved by the joint-stock two-year myth. For a natural person there is a capital gain, PPI-indexed cost and a TL 150,000 exemption in 2026. The transfer deed is stamp-exempt; watch side protocols. Notary–general meeting–registry first; tax file second.
To build a share sale or partnership change together, see company formation and tax advisory, and send it to us. Our office is on Google Maps.